The years of stagnation in e-commerce are over. According to ECDB, growth is expected to regain its former momentum in 2026. A new global revenue threshold of US$5 trillion is expected to be surpassed this year. That represents a net increase of US$421 billion compared to 2025.
But this growth is far from evenly distributed. A closer look at the sources of global e-commerce growth reveals a familiar pattern: the same two or three markets consistently account for the lion’s share of revenue gains.
This points to a clear trend toward market concentration, one of many insights found in the report *ECDB Global E-Commerce Compass*. In the following joint analysis by ECDB and Digital Commerce Finland, we examine which companies are at the center of this concentration.
Global E-Commerce Exceeds US$5 Trillion Amid Market Recovery
A normalization of e-commerce revenues following the pandemic’s peak led to temporary dips in the years that followed. That phase now appears to be over. Growth has rebounded, and the industry is reaching new milestones.
In 2026, global e-commerce revenues are projected to exceed US$5 trillion. More specifically, analysts expect global e-commerce to generate US$5.31 trillion this year. This puts the sector on par with the GDP of major economies such as Germany or Japan.
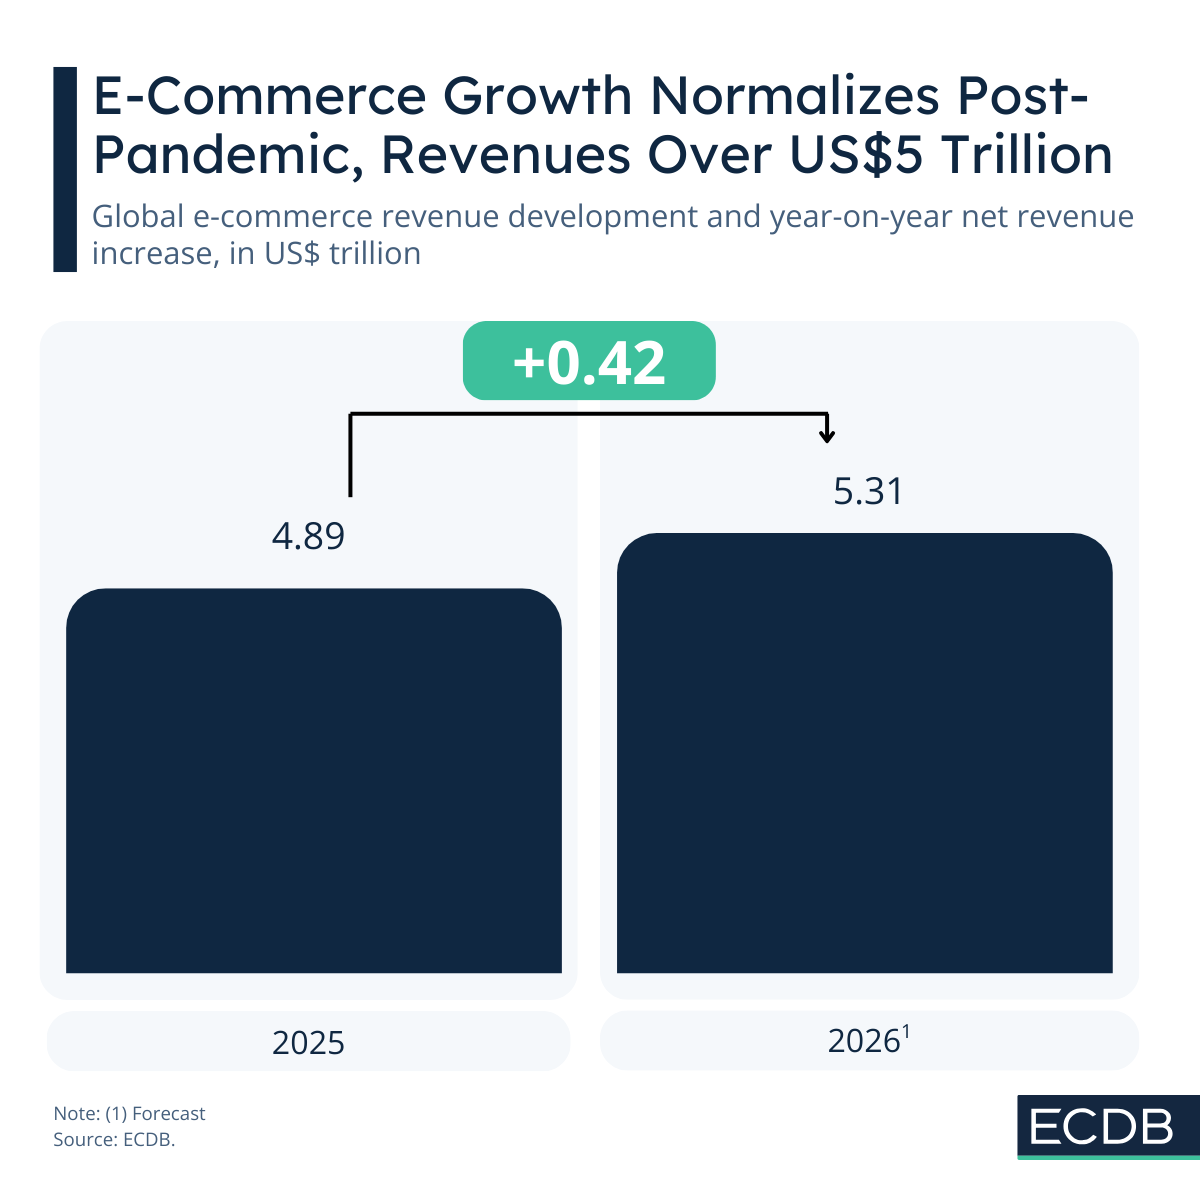
In absolute terms, growth since 2025 represents a net increase of US$421 billion. But its distribution tells a more nuanced story.
Global E-Commerce Growth Is Concentrated in a Few Markets
Net growth highlights where revenue is actually increasing in absolute terms. This contrasts with relative growth, which tends to highlight smaller markets due to higher percentage increases, even if their overall contribution remains limited.
Consider this year’s net growth as an illustration of this trend. Of the US$421 billion increase in revenue, 42% came from Greater China, the largest e-commerce market. The United States followed, accounting for 19% of net revenue growth. The third-largest market, the United Kingdom, contributed US$12 billion, or 3%, to this growth.
Together, the three largest e-commerce markets account for 64% of global e-commerce growth. The remaining US$153 billion is distributed across the rest of the world.
A representation based solely on percentages therefore fails to account for the scale and concentration effects that determine where most of the absolute revenue gains are generated. This also affects e-commerce retailers.
Chinese E-Commerce Giants and Their International Expansion
At the company level, concentration is somewhat less pronounced, but still significant. The three largest players account for 39% of global net revenue growth. This distribution among Pinduoduo, TikTok (Douyin), and Amazon leaves more room for other players to contribute.
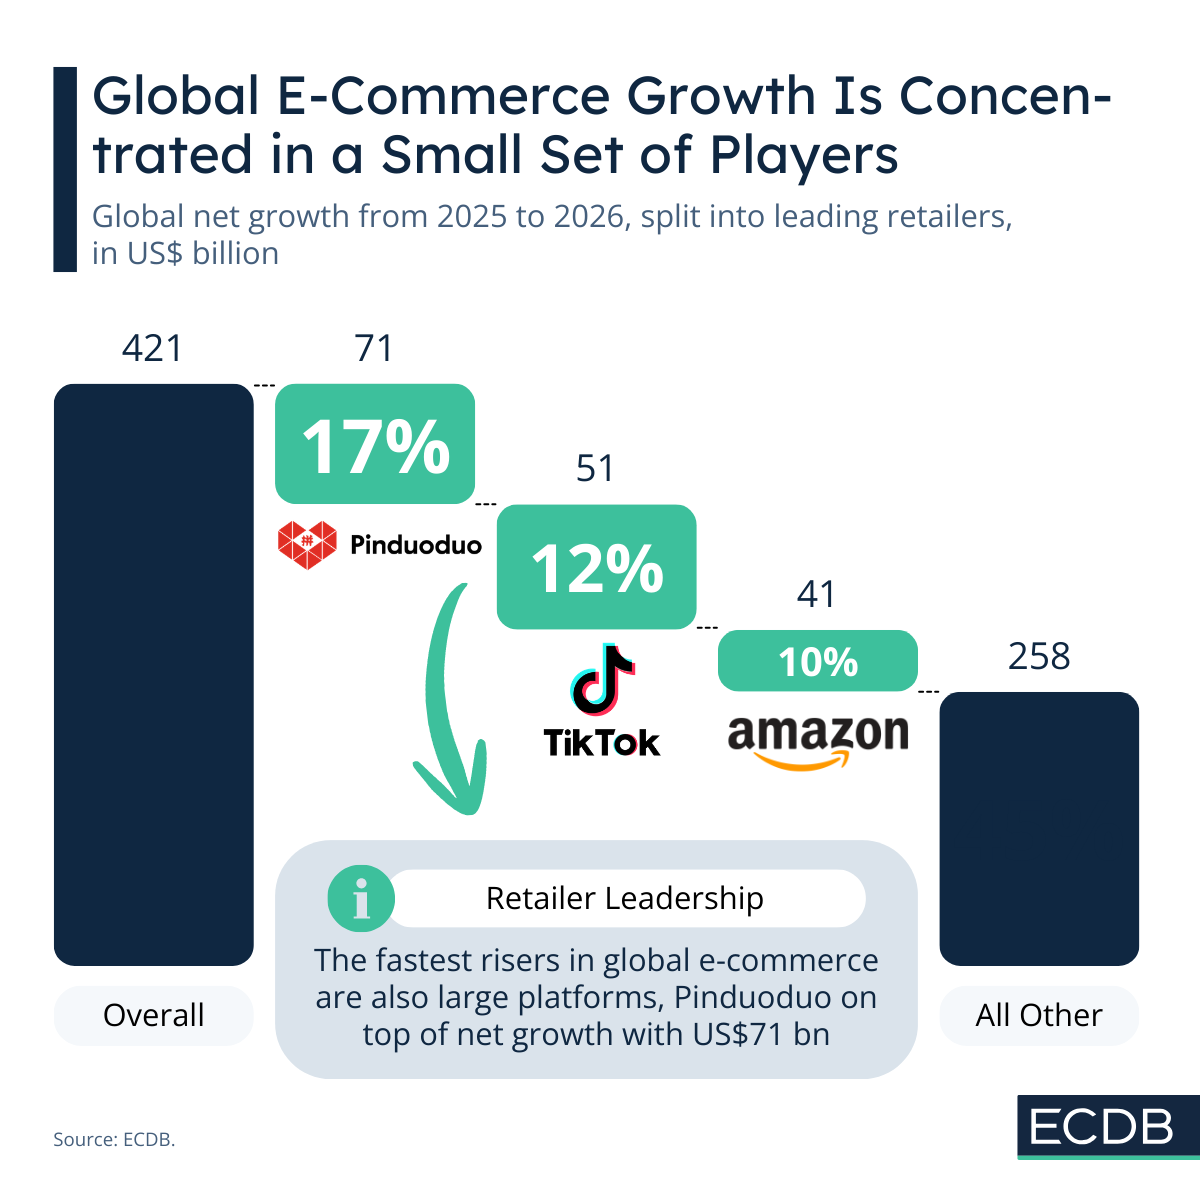
Nevertheless, this portrayal underscores China’s prominent role. The two leading retailers, Pinduoduo and Douyin, are both major Chinese players with significant operations abroad. Pinduoduo’s sister platform, Temu, is rapidly gaining ground across multiple e-commerce markets; in Finland, for example, it is currently the leading platform.
Similarly, Douyin is expanding internationally through TikTok Shop, with a strong presence in Southeast Asia and the United States. Its presence in Europe is also growing, although it has yet to gain the same level of traction.
Amazon, by contrast, remains the global leader. Its presence in China and Asia more broadly is relatively limited. It continues to be a major driver of e-commerce concentration in the U.S., even as the United States lags behind China overall.
Growth Patterns Reinforce the Dominance of China and the United States
While growth trends highlight change, the total market size reflects continuity. Global e-commerce remains dominated by two players: China and the United States.
China is in a league of its own, with market revenues of US$2.2 trillion and year-on-year growth of 8.6%. The United States also significantly outpaces other competitors, but still lags far behind China by approximately US$1 trillion.
China is also ahead of the United States in terms of growth, with year-on-year increases of 8.6%, compared to 7.4%. Among the top 10 countries, India and Russia are the fastest-growing, at rates of 13.2% and 11.6%, respectively.
Despite this, none of the lower-ranked markets come close to the scale of the two leading economies. Even high-growth emerging markets such as India, Russia, and Brazil, despite their large consumer bases, remain far behind in absolute terms.
In effect, concentration reinforces itself: leading markets capture the largest share of net revenue growth, further cementing their dominant positions.
China and the U.S. Account for 64% of Global E-Commerce Revenues
Relatively speaking, that concentration holds true: 64% of global e-commerce revenue is generated by China and the United States. The remaining 36% comes from the rest of the world.
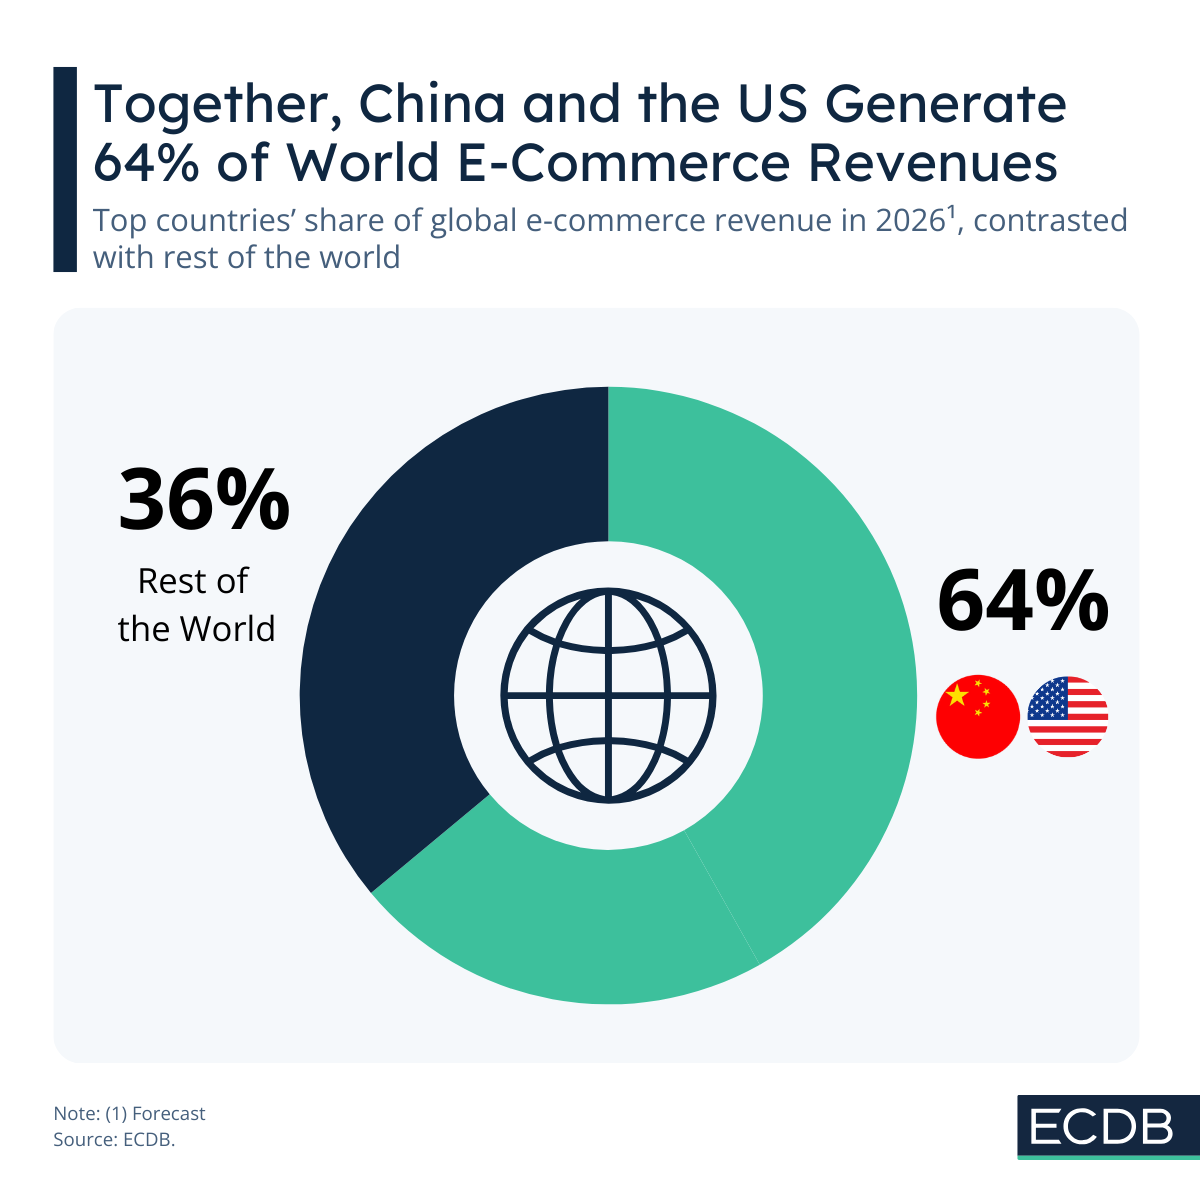
This fact has significant implications for current political developments, because tariffs and trade barriers further reinforce the existing concentration by making cross-border competition more costly for smaller or emerging markets.
Outlook: Market Concentration Shapes the Global E-Commerce Landscape
Market concentration is a defining force in e-commerce. The dominance of China and the United States is reflected in two ways: on the one hand, through current market size, and on the other, through new revenue contributions. As these two markets account for the majority of incremental growth, their lead over the rest of the world continues to widen.
For companies, success in global e-commerce will depend on how effectively they position themselves within or alongside dominant ecosystems. For smaller and emerging markets, the challenge lies in remaining competitive despite structural disadvantages that are amplified by scale and, increasingly, by geopolitical factors. If you’re interested in more analyses like these, check out Friedrich Schwandt’s talk at the eCom Summit on May 21!